Aave App Review: Is a 6% Stablecoin Savings Rate Worth the Waitlist?
The Aave App reviewed: where its 6.00% base rate comes from, what code DFBC07 does on the waitlist, funding and withdrawals, Balance Protection, self-custody risks, who can use it and who should skip it.
Last updated 24 October 2026
Best for
iPhone users who already hold, or are happy to buy, US dollar stablecoins, want a variable savings rate well above a bank's, and accept that there is no deposit insurance behind it.
The Aave App is a working savings product now, not just a sign-up list. Its iPhone app pays a variable 6.00% base rate on dollar stablecoins, or up to 6.25% if you set up monthly deposits of $1,000 or more: about $600 a year on $10,000 if the rate holds. Code DFBC07 moves you up the waitlist and does nothing else: no cash, no tokens, no rate boost. Join if a self-custody wallet and stablecoin risk suit you, and treat the rate as variable; keep emergency money in an insured bank account.
Pros
- A 6.00% variable base rate, or up to 6.25% with $1,000 or more of monthly deposits, compounded every second
- Self-custody: your key is created on your phone, and Aave Labs says it can't move your funds
- Fund with USDC, USDT or GHO, or by bank transfer through Push in the US, UK and EEA after an ID check
- No app fee, minimum or lock-up on the App Store listing; you can withdraw at any time
- Balance Protection of up to $100,000 for eligible customers, although it isn't insurance
- Joining the waitlist costs nothing, and DFBC07 moves you up it
Watch-outs
- The rate is variable and Aave's own disclosures say it can be cut to 0%
- No FDIC, FSCS or other deposit insurance: Aave says plainly that it isn't a bank
- iPhone only (iOS 18.4 or later); Android and web are still on a waitlist
- DFBC07 pays nothing: it only moves you up the waitlist
- Smart-contract, stablecoin and lost-key risks are yours, and transactions can't be reversed
- Disputes go to arbitration under Cayman Islands law unless you opt out within 30 days
Current related offer
Aave App offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Aave App
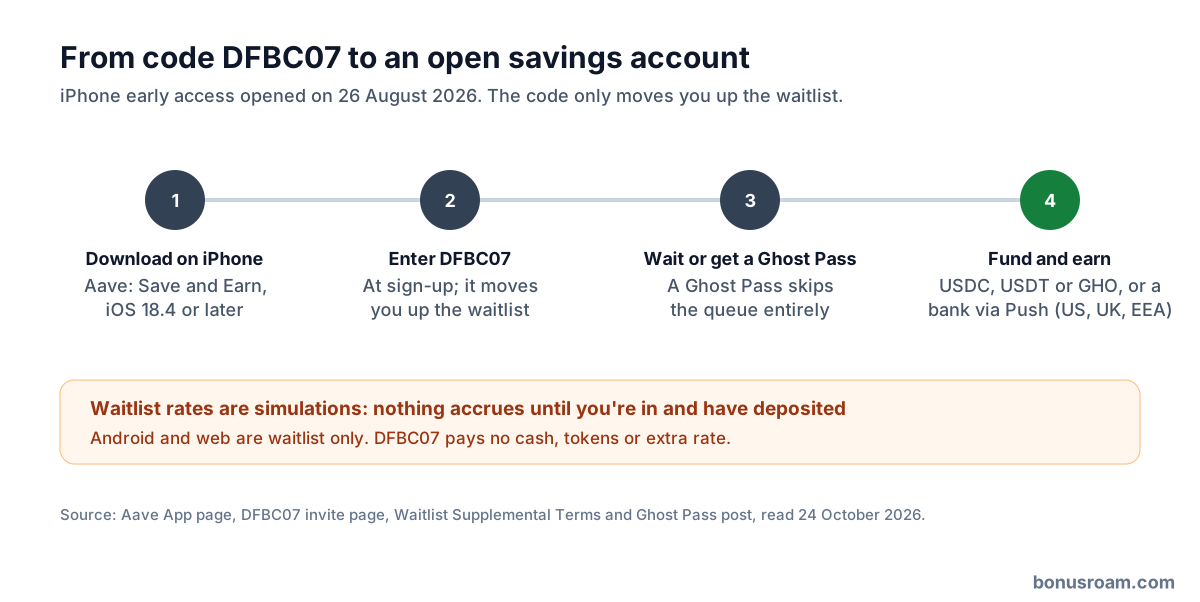
Aave's app, Aave: Save and Earn, has been in early access on iPhone since 26 August 2026. Download it on an iPhone (iOS 18.4 or later) and enter referral code DFBC07 at sign-up; the invite page says the code moves you up the waitlist. It is not a cash, token or yield offer, so only sign up if you already want to use Aave's app.
Requirement: No deposit; waitlist sign-up only
Easy2-5 minutesPayout Waitlist access only; no guaranteed payout
Verified 24 October 2026
Full claim instructions are on the Aave App offer page.
What the Aave App is
Aave is one of the largest lending protocols in decentralised finance, and the Aave App, listed on the App Store as "Aave: Save and Earn", is its consumer savings app. Aave Interfaces Ltd, part of Aave Labs, publishes it, and its terms are governed by Cayman Islands law. Aave calls it "the world's savings app" and says plainly that it is not a bank.
It is self-custodial: the app creates a wallet on your phone, the private key never leaves your device in readable form, and Aave Labs says it can't access or move your money. Early access opened on 26 August 2026 on iPhone (iOS 18.4 or later). Android and web users join a waitlist.
Where the interest comes from
The dollars you save sit in a vault that lends stablecoins to borrowers on the Aave protocol. Those borrowers must post more collateral than they borrow, and the interest they pay funds your rate. Interest compounds every second and shows in the app in real time.
The rate is set, not earned one-for-one: the Aave DAO sets the rate paid to app users within approved limits, and Aave Labs keeps the difference between what the vault earns and what you are credited. That spread is how the app is paid for. Aave's disclosures add that permissioned roles can change the rate, "including to 0%", and can restrict deposits or withdrawals in an emergency.
The rate: 6.00% base, up to 6.25%
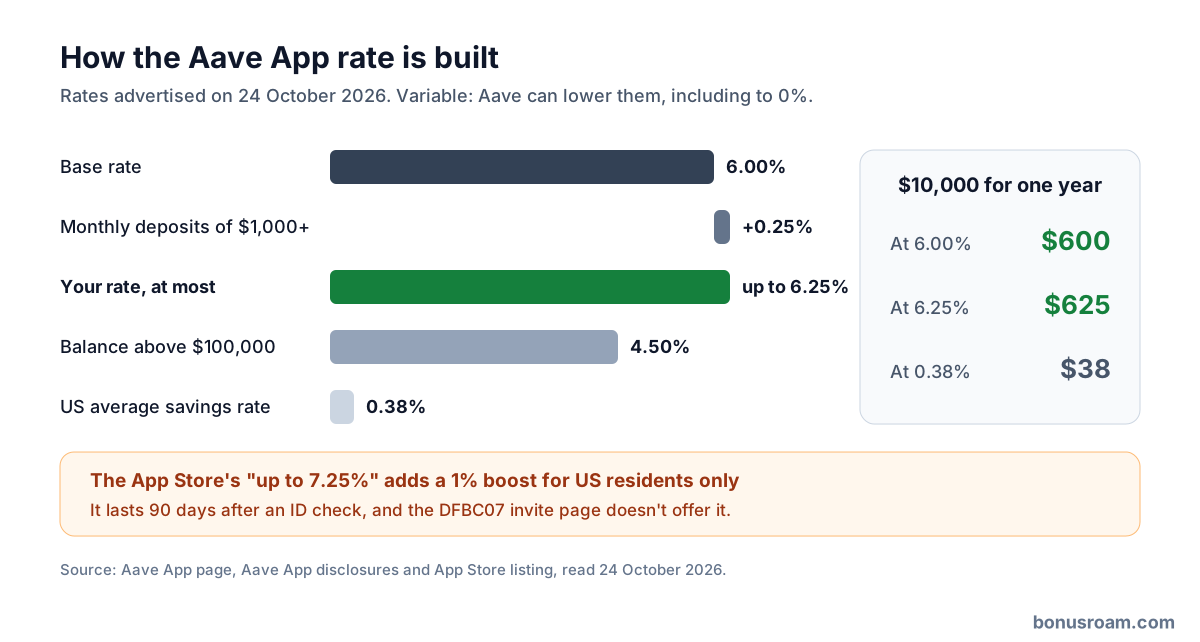
On 24 October 2026 Aave advertised a 6.00% base rate plus boosts, for up to 6.25% a year. The one boost it describes is 0.25% for setting up monthly deposits totalling $1,000 or more. Any balance above $100,000 earns 4.50%. Rates vary by region and account, and Aave says they are variable and can fall.
The App Store listing says "up to 7.25%". The extra 1% is a referral boost Aave offers US residents for 90 days after an identity check. The DFBC07 invite page doesn't include it, so plan on 6.00% to 6.25%.
What code DFBC07 does
The DFBC07 invite page tells you to download the app and enter the code at sign-up "to move up the waitlist". That is the whole benefit. It pays no cash, no tokens and no extra rate, and Aave's waitlist terms say joining doesn't promise access, a launch in your country or any return.
The queue moves through Ghost Passes: invitations that skip the waitlist entirely. Aave sends them in batches to early sign-ups, to people who refer friends and to active social accounts, and existing users can pass theirs on. While you wait, any rate or boost the app shows is a simulation; no interest accrues until you are in and have deposited.
Disclosure: DFBC07 is our own code. Each sign-up with it counts as one of our referrals, which Aave uses when it ranks the waitlist and hands out Ghost Passes. Neither side gets cash.
What it's worth: a worked example
Put $10,000 in and leave it for a year. At the 6.00% base rate you earn about $600; with the 0.25% deposit boost, about $625. Aave's own comparison is the US national average savings rate of 0.38% (as of 17 August 2026), which pays about $38 on the same money.
Larger balances earn less on the top slice: $150,000 earns about $6,000 on the first $100,000 and $2,250 on the other $50,000, or $8,250 in total. Every point the rate drops costs $100 a year on $10,000, so check the live rate before moving more money in.
Adding and withdrawing money
You can send USDC, USDT or GHO to the app on a supported network; Arbitrum came first and USDC on Base followed. In the US, UK and EEA you can also link a bank account through Push, Aave Labs' payments business, after verifying your identity.
Withdrawals go to a bank through Push or to a wallet address you have pre-approved with a one-time code. The App Store listing promises no fees, no minimums and no lock-ups. Network gas and stablecoin swap costs still apply, and Aave's disclosures allow governance-approved withdrawal fees.
Protection, regulation and who holds what
Balance Protection is a discretionary programme for eligible customers, advertised as up to $100,000 of account protection. Aave stresses that it is not insurance and doesn't promise to repay every loss, and the full terms sit inside the app. No government scheme such as FDIC or FSCS covers your balance.
The bank rails are regulated, the app is not. Push Virtual Assets Ireland Limited is authorised by the Central Bank of Ireland under MiCA; in the UK, Push Labs Limited is an FCA-authorised e-money institution (FRN 900984) and FCA-registered for cryptoassets; in the US, Bridge and Astra provide the money transmission. Aave states that these licences don't extend to the app or its savings vault.
Risks and catches
Your dollars are stablecoins lent through smart contracts. A contract bug, a stablecoin losing its peg, bad debt or a run on the vault could delay withdrawals or lose money, and transactions are final, with no chargeback. Nine security firms have reviewed the code, which lowers the risk but doesn't remove it.
Self-custody cuts both ways. If you lose your phone and every recovery method (another signed-in device, or the optional biometric recovery run by CoinCover), the money may be gone for good. Aave can also suspend the service or block an account without notice, and disputes go to binding arbitration in the Cayman Islands unless you opt out within 30 days of accepting the terms.
Who can use it
You must be 18 or the age of majority where you live, whichever is higher, and not in a sanctioned country. The terms exclude residents of Belarus, Côte d'Ivoire, Cuba, Iran, Iraq, Liberia, Libya, Myanmar, North Korea, Russia, Sudan, Syria, Venezuela and the occupied regions of Ukraine, and using a VPN to get around this can close the account.
Elsewhere, Aave says availability and features vary by country: the app tells you what applies after you sign up. Bank funding exists only in the US, UK and EEA; everyone else funds with stablecoins. You need an iPhone for now.
What users complain about
On 24 October 2026 the app was rated 4.7 from 321 ratings on the US App Store. Most reviews praise the design and the rate.
The recurring complaints are the personal data asked for at sign-up (email, phone and, in the US, a Social Security number), being locked out after changing phones, a long wait with nothing to do on the waitlist, boosted rates that depend on referrals, and the point that the app isn't the same as using the permissionless Aave protocol directly.
Who should join, and who should skip it
Join with DFBC07 if you have an iPhone, want a dollar savings rate around 6%, and are comfortable that a variable rate, smart contracts and a self-custody wallet replace a bank's deposit insurance. Start with a sum you could leave untouched through a market scare.
Skip it if you need deposit insurance, would panic at a frozen withdrawal, can't keep your recovery methods safe, or live where the app or its bank rails aren't offered. And don't join expecting a token airdrop or cash for using the code: neither is on offer.
FAQ
- Is the Aave App a bank account?
- No. It is a self-custody savings app that lends dollar stablecoins through the Aave protocol. Aave says it isn't a bank, and no deposit insurance scheme covers it.
- What does code DFBC07 give me?
- A higher place on the waitlist. It pays no cash, tokens or extra interest.
- Do I earn interest while I'm on the waitlist?
- No. Rates and boosts shown on the waitlist are simulations; interest starts once you have access and deposit.
- How do I get off the waitlist faster?
- Sign up with DFBC07, then watch for a Ghost Pass. Aave sends them in batches to early sign-ups, active referrers and social followers, and existing users can share theirs.
- What rate will I actually get?
- On 24 October 2026, 6.00% as a base rate, up to 6.25% with $1,000 or more of monthly deposits, and 4.50% on balances above $100,000. The rate is variable.
- Is my money protected?
- Partly. Balance Protection covers eligible customers up to $100,000 under terms in the app, but Aave says it isn't insurance and doesn't promise to repay every loss.
- Can I use it on Android or a computer?
- Not yet. The app is iPhone only for now; Android and web users join a waitlist.