SuperCash Review: Stablecoin QR Payments, a US Dollar Account and What Code BWUFID Saves
SuperCash reviewed: how the self-custodial wallet pays local QR codes in seven countries and bank accounts in Nigeria, the Global USD Account and its 0.5% deposit fee, what code BWUFID saves, limits with and without KYC, the exchange-rate spread and who should skip it.
Last updated 24 October 2026
Best for
Freelancers and remote workers in the Philippines, Vietnam, Brazil, Colombia, Peru, Bolivia, Argentina or Nigeria who are paid in US dollars and want to spend them locally by QR code or bank transfer.
Useful if you earn in dollars and live in one of its eight countries; of no use anywhere else. With our code BWUFID, your first Global USD Account deposit is fee-free up to $3,000, which saves up to $15 against the normal 0.5%; there's no spending task and no cash bonus for you. After that you pay 0.5% on incoming dollars and an exchange rate 0.5% to 1.0% from mid-market when you pay locally, so a $1,000 payout spent in the Philippines costs roughly $10 to $15. SuperCash itself isn't regulated: a Hong Kong company runs the app, and licensed partners it doesn't name handle the dollar accounts, conversion and settlement. It's also young, on the App Store only since April 2026 and with too few ratings to judge.
Pros
- Code BWUFID makes your first USD deposit fee-free, up to $3,000, with no spending task
- US routing and account numbers in your name, with no SSN, US address or local bank account needed
- Pays local QR codes in seven countries and bank accounts in Nigeria straight from USDC or USDT
- Self-custodial: SuperCash says it can't hold, freeze or lock your balance
- Spending without identity checks: $500 a day, or $2,000 in Vietnam and the Philippines
- Nothing to pay to open or keep the account, or to withdraw stablecoins on-chain
Watch-outs
- Only useful in eight countries: Vietnam, the Philippines, Brazil, Colombia, Peru, Bolivia, Argentina and Nigeria
- 0.5% on every later USD deposit, plus a 0.5% to 1.0% spread when you pay locally
- A new app: one App Store rating and no Google Play score yet
- The regulated parts come from third-party partners SuperCash doesn't name
- Lose access to your login and SuperCash can't recover the wallet
- No deposit protection: USDC and USDT balances aren't bank deposits
Current related offer
SuperCash offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
SuperCash
SuperCash is a self-custodial stablecoin wallet that lets you pay local merchants by scanning their QR codes or sending a bank transfer, converting USDC or USDT to local currency at the point of payment. The BWUFID invite page offers a zero-fee USD deposit up to US$3,000 on your first deposit. Not available in the UK — SuperCash currently highlights Vietnam, the Philippines, Brazil, Colombia, Bolivia, Peru, Nigeria and Argentina. The operator is LinkGen Limited, Wan Chai, Hong Kong.
Requirement: No spend required; apply BWUFID before your first Global USD Account deposit (KYC required)
Medium10-15 minutesPayout Applied to your first Global USD Account deposit when BWUFID is on the account
Verified 24 October 2026
Full claim instructions are on the SuperCash offer page.
What SuperCash is
SuperCash is a stablecoin wallet app for people who earn in US dollars and spend in a local currency. It's run by LinkGen Limited, a company in Wan Chai, Hong Kong, and has been on the App Store since April 2026, with Android and web versions too. Signing up with Google, Apple or an email creates a self-custodial wallet through SuperCash's technology partner, Dynamic, protected by a PIN and your phone's biometrics, so there's no seed phrase to write down.
SuperCash describes itself as a technology provider, not a bank, payment institution or regulated financial firm. The regulated parts, meaning the US dollar account, currency conversion and settlement into local payment networks, are done by licensed third-party partners under their own authorisations; SuperCash doesn't name them. You must be 18 or over.
How a payment works
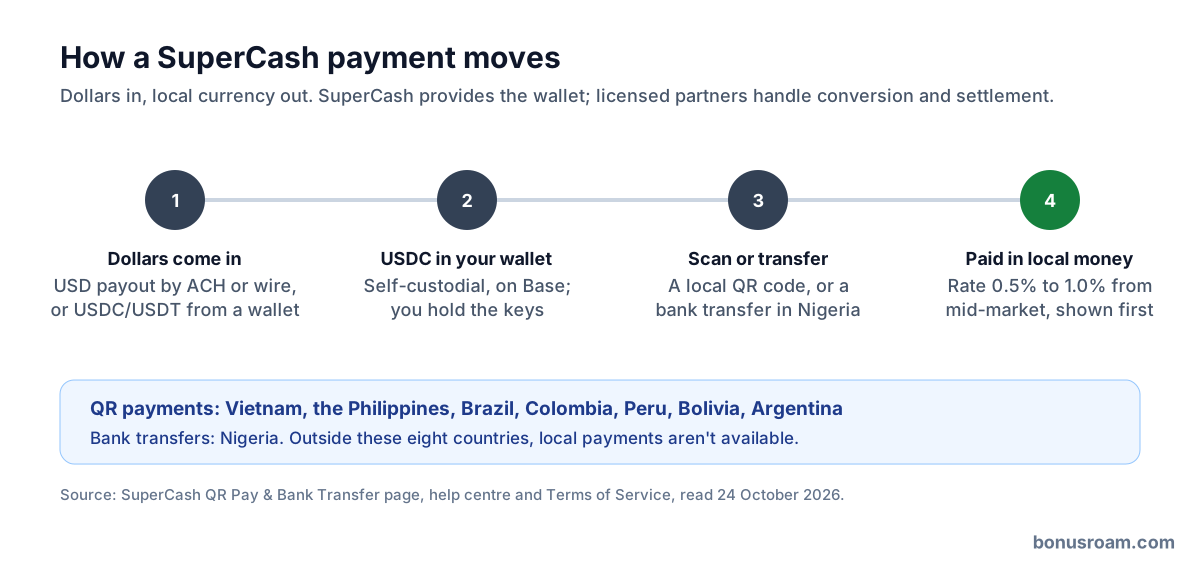
You fund the wallet with USDC (on Arbitrum, Base or BNB Smart Chain) or USDT (on Arbitrum or BNB Smart Chain), or with dollars paid into your Global USD Account, which arrive as USDC on Base. To pay, you scan a merchant's QR code or enter local bank details, check the amount and rate, and confirm. The stablecoins go on-chain straight to the partner's address, and the partner pays the merchant in local currency.
The coverage is specific: VietQR, MoMo and bank QR codes in Vietnam; QRPh, InstaPay and transfers to GCash and Maya in the Philippines; Pix in Brazil; local QR codes in Colombia, Peru (including Yape and Plin), Bolivia and Argentina; and bank transfers to any Nigerian bank. Outside those eight countries, SuperCash can't make local payments.
The Global USD Account
The account gives you US routing and account numbers in your own name, for payouts from Upwork, Fiverr, Deel, PayPal, Outlier AI, Handshake AI or a client paying by ACH or domestic wire. You don't need an SSN, a US address, an LLC or a local bank account. ACH payments take one to two business days to clear; domestic wires arrive the same day if they're sent during US banking hours, Monday to Friday.
To open it you pass KYC: your full legal name, an email, a passport, driving licence or residence permit (national ID cards aren't accepted) and a liveness scan, in the app or on SuperCash's web portal. Every deposit pays a flat 0.5%, with no minimum fee, and converts automatically to USDC on Base in your wallet. There's no account opening or maintenance fee.
Code BWUFID: what it gets you
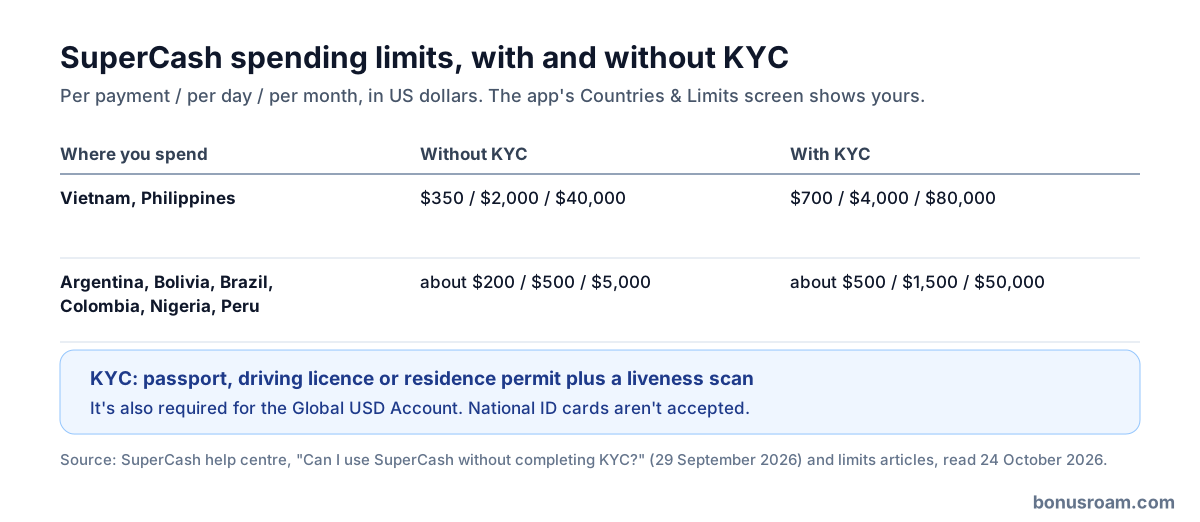
Apply our code BWUFID and your first Global USD Account deposit after applying it is free of the 0.5% fee, up to $3,000. Our link carries the code into sign-up; if you've already registered, add it under Profile or Settings, then Referral Code, then Apply. There's no spending task and no cash reward for you: the fee waiver is the whole benefit, worth up to $15.
Bind the code before your first payout lands, because the waiver covers the first deposit after you apply it. Disclosure: BWUFID is our own code. SuperCash pays us $1 when you deposit more than $100 into your USD account and $1 when you spend more than $100 by QR or bank transfer, each within 90 days of applying the code, settled monthly.
What it's worth: a worked example
A first payout of $3,000 normally costs $15 to deposit; with BWUFID it costs nothing. A $1,000 first deposit saves $5 and $500 saves $2.50. It's a one-off: every later deposit pays the full 0.5%.
The running cost decides whether SuperCash suits you. A $1,000 monthly payout costs $5 to deposit, and spending it all by QR in the Philippines costs another $5 to $10 in exchange-rate spread: about $10 to $15 a month, or 1% to 1.5%. The rate on screen before you confirm is all-inclusive, so compare it with your bank's on the same day before you move a large payout.
Limits, with and without KYC
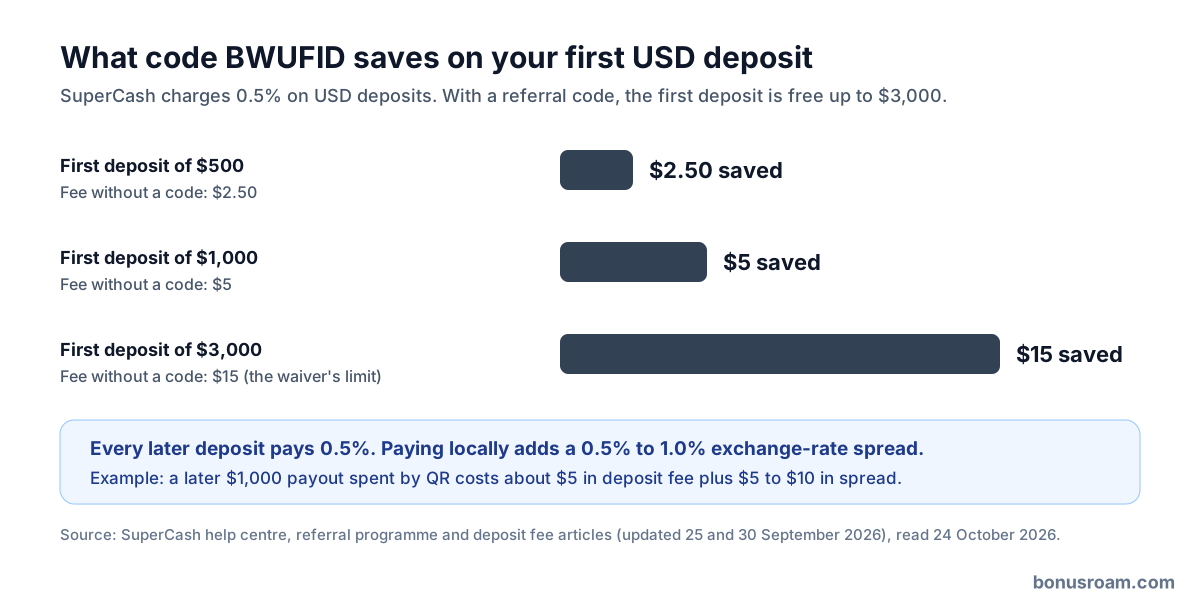
You can spend without identity checks, within limits that depend on where you pay. In Vietnam and the Philippines: $350 per payment, $2,000 a day and $40,000 a month. In Argentina, Bolivia, Brazil, Colombia, Nigeria and Peru: about $200 per payment, $500 a day and $5,000 a month.
KYC raises those to $700, $4,000 and $80,000 in Vietnam and the Philippines, and to about $500, $1,500 and $50,000 elsewhere, as soon as you're approved. The Google Play listing advertises up to $3,000 a day without KYC, more than the help centre's figures; the Countries & Limits screen in the app shows the limits that apply to you.
Fees in full
SuperCash charges nothing to open or keep the account, nothing for same-token payments and nothing to withdraw stablecoins to your own wallet or an exchange, although normal network fees can apply to on-chain transfers. USD deposits pay 0.5%. Local QR payments and bank transfers carry no separate fee, but the exchange rate sits 0.5% to 1.0% from the mid-market rate.
A convenience fee can apply when a payment needs a token swap, and partners' fees, rates and spreads are built into the quote you see before confirming. There's no minimum deposit for USDC or USDT, but network fees can eat very small deposits, and tokens sent on an unsupported network may be lost for good.
Custody, recovery and protection
SuperCash says it never has your private keys and can't hold, freeze or lock your balance. The other side of that is in its terms: you alone are responsible for keeping access to your wallet and recovery credentials, and if you lose access, SuperCash can't recover the funds.
Nothing here is deposit-protected. USDC and USDT aren't bank deposits, a stablecoin can lose its peg, and once you've sent funds to a partner for settlement, any dispute, delay or refund is between you and that partner, not SuperCash. The partners also make the KYC and account decisions.
What users say
There isn't much to go on yet. On 24 October 2026 the iPhone app had a single rating on the US App Store (5.0), and the Android app, with more than 1,000 downloads, had too few reviews for Google Play to show a score.
So no complaint pattern has formed. Start small: one payout to the USD account, one QR payment at a shop you use, and a look at the on-screen rate against your bank's rate that day.
Who should use it, and who should skip it
Use it if you're paid in dollars by platforms or clients and live in one of the eight countries, especially the Philippines or Vietnam, where the limits are highest. Apply BWUFID before your first payout to take the free deposit.
Skip it if you live anywhere else, if your income isn't in dollars, if you need deposit protection, or if you'd rather your money sat with a regulated provider you can name.
FAQ
- Where does SuperCash work?
- For local payments, in eight countries: QR codes in Vietnam, the Philippines, Brazil, Colombia, Peru, Bolivia and Argentina, and bank transfers in Nigeria.
- What does code BWUFID give me?
- A 0% fee on your first Global USD Account deposit after applying it, up to $3,000. That saves up to $15; there's no cash bonus.
- Do I have to spend anything to get it?
- No. The waiver applies to your first USD deposit after you bind the code; there's no spending requirement.
- I've already signed up. Can I still add the code?
- Yes. In the app, go to Profile or Settings, then Referral Code, enter BWUFID and tap Apply, before your first USD deposit.
- Do I need to verify my identity?
- Not to spend within the unverified limits. You need KYC for the Global USD Account and for higher limits.
- What does SuperCash cost?
- 0.5% on USD deposits and an exchange rate 0.5% to 1.0% from mid-market on local payments. No account, maintenance or on-chain withdrawal fee.
- Which stablecoins and networks can I deposit?
- USDC on Arbitrum, Base or BNB Smart Chain, and USDT on Arbitrum or BNB Smart Chain. Other networks risk permanent loss.
- Is my balance protected?
- No. SuperCash is self-custodial and not a bank, so USDC and USDT balances have no deposit insurance, and SuperCash can't recover a wallet you lose access to.